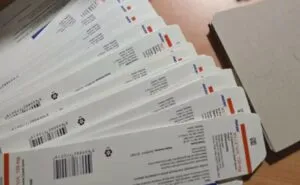
Cancer Drug in a First Aid Kit at Bogorodica: Why Was the Driver Also Carrying 30 Labels?
22.10.2026


22.10.2026
22.10.2026
22.10.2026
22.10.2026
22.10.2026
22.10.2026

22.10.2026
21.10.2026
20.10.2026
22.10.2026
22.10.2026
21.10.2026
22.10.2026
22.10.2026
22.10.2026
22.10.2026
21.10.2026
20.10.2026
22.10.2026
22.10.2026
21.10.2026
22.10.2026
21.10.2026
20.10.2026
20.10.2026
19.10.2026
17.10.2026
23.04.2026
23.04.2026
12.04.2026
As of September, citizens and companies together owe the banks 9.87 billion euros. Of that, citizens owe 4.93 billion and companies 4.90 billion euros. In September alone total debt grew by 1.3 percent, and year on year by 14.1 percent - 15.7 percent for companies, 12.7 percent for households. That's according to the latest figures from the National Bank.
At the same time, deposits are growing more slowly - 9.2 percent a year, to 11.15 billion euros, of which 7.5 billion belong to citizens. The gap of almost five percentage points says something simple: we're borrowing faster than we're saving.
Housing loans are growing fastest - 16.1 percent in one year. Consumer loans are up 12.4 percent. But a smaller number says the most: negative balances on current accounts, the overdraft the bank hands you when your salary doesn't stretch to the end of the month, jumped 5.8 percent in September - in a single month.
The rise in housing loans doesn't necessarily mean more people are buying flats. When flat prices rise, so does the amount you have to borrow to buy one. For many families, a home of their own means a monthly instalment to the bank for the next 20 or 30 years, at an average lending rate of 4.67 percent in August.
The National Bank is reacting. From December 1, the repayment period for a second or any further home drops from 30 to 25 years, mortgage loans are capped at 15 years, and the maximum share of salary that can go to an instalment falls from 50 to 45 percent for denar loans and from 45 to 40 percent for euro loans. For a first home, the term stays at up to 30 years.
The measure is reasonable - but it treats the consequence. When loans grow faster than savings, the question isn't only how long we'll be paying them off, but why we need so much credit for basics like a roof over our heads. That question isn't the central bank's to answer. It's the government's.
The latest 10 news from this category
Revenue of 3.39 instead of 1.88 billion denars, for 5.68 instead of 6.24 billion kilowatt-hours. The bill could rise 4...
A four-year-old with a million-denar income from a bank dividend, an annual salary of 2.2 million euros in mining and...
Revenue grew 26 percent, costs 68. The answer is a new class of shares: investors bring in money, and the...
Three founders and a promise that AI can be trained on far less data. In Silicon Valley that's now worth...
You pay a cleaning fee, then get a list of chores on your way out. For bookings from November 20...
The union's consumer basket reached 70,358 denars, and almost the entire monthly increase is on the dinner table. The government...
The amendments passed their first parliamentary filter. Your flat is yours, the land under it still belongs to the state,...
Three hours today, five tomorrow, and pay by the hour. It sounds like flexibility, but the question remains who decides...
The company that sells artificial intelligence is now also offering the law that would control it. The checkers would be...
A company from a small Baltic country raised 100 million dollars to tell humans from machines online. The trick is...
This site uses cookies - is that okay? Learn more
Be the first to know when Metla launches something new
Leave your email and we will write when there is a new guide or something new on Metla.