The Mihailova Case Goes to NATO: Mickoski Blames Sofia, and the Interior Ministry Still Hasn't Explained How She Crossed the Border
17.10.2026


17.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
16.10.2026
15.10.2026
17.10.2026
17.10.2026
16.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
16.10.2026
15.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
17.10.2026
16.10.2026
15.10.2026
15.10.2026
13.10.2026
12.10.2026
23.04.2026
23.04.2026
12.04.2026
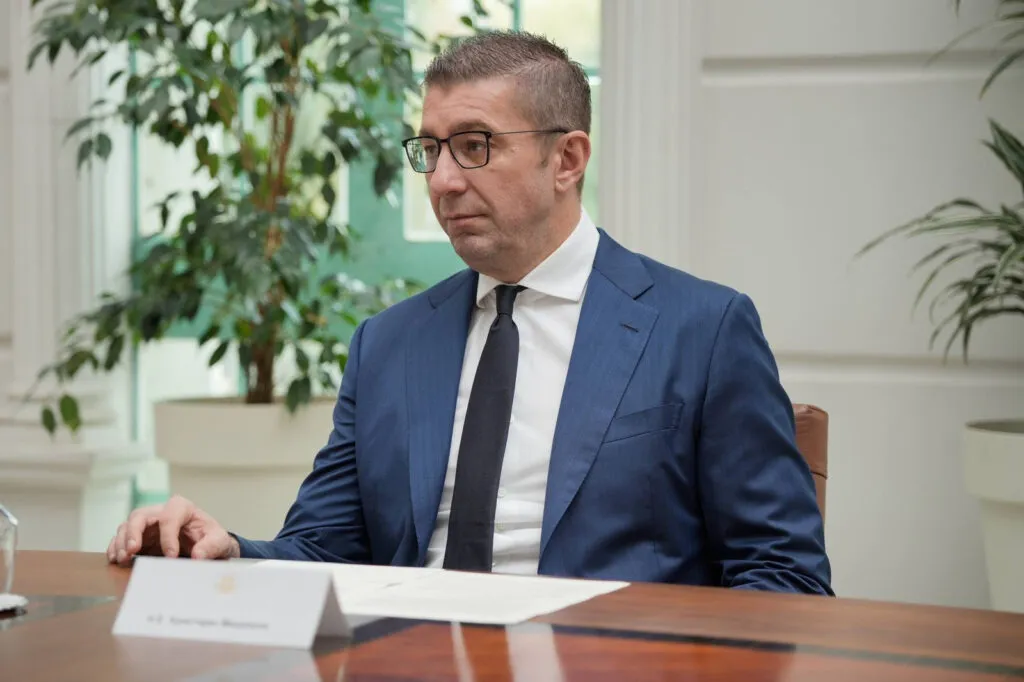
The Ministry of Social Policy, Demography and Youth has sent Parliament its proposed amendments to the Law on Mandatory Fully Funded Pension Insurance. That makes it clear the second pension pillar won't be shut down, nor will the money be moved into the state Pension Insurance Fund, a topic Prime Minister Hristijan Mickoski himself opened when he mentioned the possibility of nationalising the assets.
Instead, multi-funds are coming. Each mandatory pension fund will have three portfolios: growth, balanced and conservative. Growth is for younger people, with riskier investments and the highest expected return. Conservative is for those close to retirement, with low risk, low return and high liquidity.
The choice will depend on age. Members up to 45 will be able to choose the growth or balanced portfolio, those between 45 and 57 any of the three, and those over 57 the balanced or conservative one. Anyone who doesn't choose will be assigned automatically: up to 45 to growth, 45 to 57 to balanced, and over 57 to conservative. Pension companies will have to inform members of the rules before they sign the contract.
The logic is simple: a young person has time to make up losses from a bad year on the markets, an older one doesn't. But here the warning that is rarely said out loud applies: a higher potential return doesn't mean a guaranteed higher pension, because every investment carries risk.
We're talking about a lot of money. The three private mandatory funds, KB Prvo, Sava and Triglav, have over 630,000 members, and their total value is around 3.5 billion euros. The PM said earlier that "a large share of second-pillar members won't be happy with what they see in their accounts." The association of pension fund management companies, for its part, warned that moving the money into the state fund would bring only temporary relief, and pointed out that the assets are personal property that can be inherited.
Multi-funds are a calmer answer than nationalisation, but they don't answer the question the PM himself raised. If people aren't happy with their accounts, was the problem that they had no choice of risk, or the size of the contributions and the returns the funds have delivered so far? For now the proposal is in parliamentary procedure, and the final rules will depend on what comes out of the MPs' benches.
The latest 10 news from this category
ESM currently sells electricity at 65 euros per megawatt-hour, while on European exchanges the price tops 200 euros. The PM...
Over 122 tonnes of animal-origin food were sent back from the border, and imports of another 21 tonnes were banned....
The agents didn't break anything - they used passwords someone had left in a public place. And India learned of...
Fakes have become so good they've earned their own name. Veritas offers a chip built into the product, and it's...
The permit is here, driverless rides are not. Maps first, then tests with a human at the wheel, and Toronto's...
The prime minister talks about GDP growth, the minister about an "option". Nobody says what the filters will cost to...
Eurostat says we're the cheapest, the unions say the basket rose by 4,355 denars in a single year. Both are...
The minister says rural women will always have the state's support. The arithmetic says the maternity money will reach 25...
816 billion parameters, open weights and a promise that it runs on a Mac. The small print: you need at...
In four months its valuation jumped by 16 billion dollars. Automating boring expense reports in America is a 60-billion business...
This site uses cookies - is that okay? Learn more
Be the first to know when Metla launches something new
Leave your email and we will write when there is a new guide or something new on Metla.